


Why does the stock market go up over time when the headlines seem to give us so many reasons for it to fall?
That question was at the center of my conversation with Brian Feroldi, a financial educator and author who has made it his mission to make investing easier to understand. What I appreciated about Brian’s story is that he did not begin as somebody who had every financial answer. He graduated with a business degree and still remembers sitting through his first 401(k) enrollment meeting trying to make sense of terms like aggressive, moderate, and conservative.
His early attempts at picking individual stocks were not exactly a victory lap, either. He lost money, felt the sting, and eventually came to view those mistakes as part of his education.
There is a useful lesson in that. You do not need to know everything before you begin learning about money, but the earlier you understand what you own, why you own it, and how it fits into a financial plan, the less likely you are to learn important lessons with much larger sums at stake.
The market is not magic. Businesses operate, innovate, compete, earn revenue, reinvest, and create value. Understanding that basic engine can make the ups and downs of investing easier to put into perspective.
Quick Answers
Why does the stock market go up over time? One important reason is that businesses grow. Companies create products and services, serve customers, reinvest, innovate, and work to increase their value. Stock prices can be volatile in the short term, but long-term market growth reflects the growth of productive businesses.
Why does the stock market sometimes fall so quickly? Markets react rapidly to uncertainty, recessions, crises, changing expectations, and fear. A sudden decline does not necessarily mean every underlying business has permanently lost its ability to create value.
Do you need to pick individual stocks to invest? No. Individual-stock research requires time, knowledge, and discipline. Investors who do not want to analyze individual companies can discuss diversified approaches with a qualified financial professional based on their circumstances.
Why should investors understand financial statements? Financial statements help explain how a company earns money, what it owns and owes, and how its financial position is changing. They provide important context for anyone attempting to evaluate an individual business.
Is the goal of investing to beat the market? Not necessarily. A financial plan should ultimately support the life you want to live. Investment decisions are tools for broader goals such as security, freedom, retirement, family, and legacy.
Why Does the Stock Market Go Up Over Time?
We understand the reasons markets can fall because those reasons make headlines. Recessions, pandemics, geopolitical events, fear, and changing expectations can all cause investors to reassess what they are willing to pay for stocks.
The recovery is often less dramatic, so it can be harder to notice what is happening underneath.
Brian’s explanation begins with the companies themselves. Businesses make products and deliver services that people and other businesses are willing to buy. Successful companies can increase sales, improve operations, introduce new products, enter new markets, and reinvest in future growth.
When you own stock, you own an interest in a business. The stock market therefore reflects more than headlines or numbers moving across a screen. Behind those prices are companies employing people, developing technology, solving problems, serving customers, and attempting to create economic value.
That does not mean every company succeeds. It does not mean markets rise every year. It certainly does not guarantee what happens next. Businesses fail, industries change, valuations move, and markets periodically experience painful declines.
But the basic mechanism matters: long-term market growth is connected to the ability of businesses to grow and create value over time.
This is also why Jesse Cramer’s perspective that smart planning beats trying to prove how smart an investor you are fits naturally here. Investing should serve the plan rather than becoming a contest against the market.
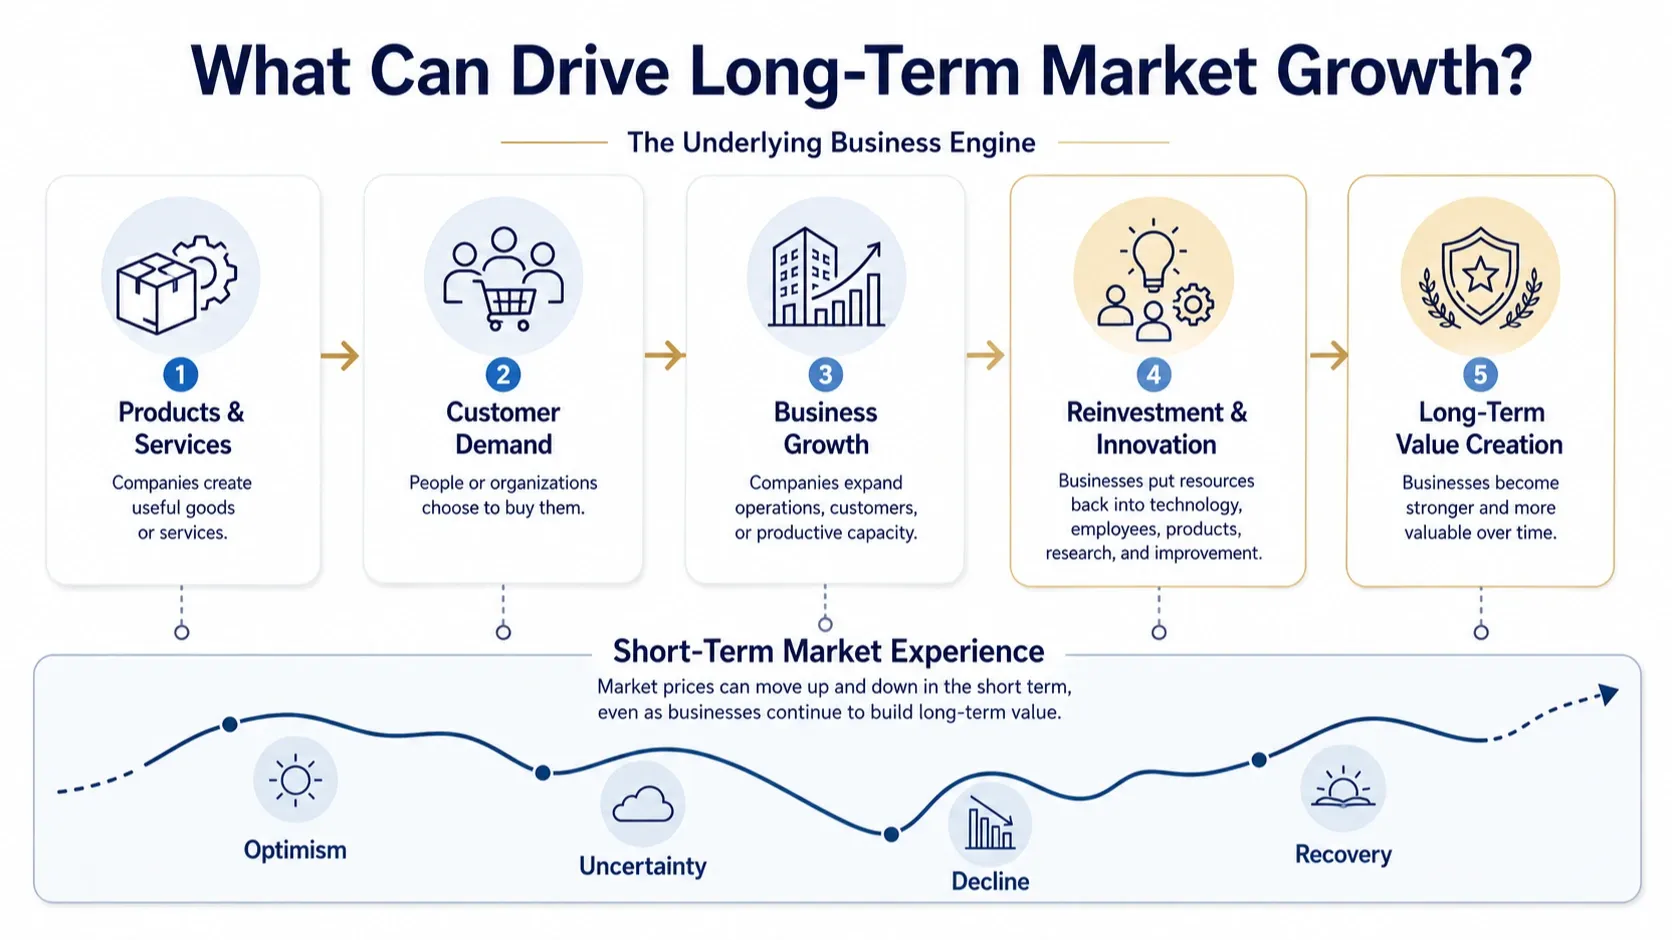
Market Declines Are Loud, but Long-Term Progress Is Quiet
One reason investing can feel so difficult is that losses get our attention quickly. A sharp market decline is visible immediately. The slow work of businesses improving products, gaining customers, investing in employees, and expanding operations rarely produces the same emotional reaction.
That difference can make investors believe the bad news is more important than everything happening in the background.
Long-term investing requires accepting that uncertainty is part of the experience. You cannot participate in market growth while simultaneously demanding that markets never decline.
This is where behavior matters. When volatility arrives, people discover whether the risk they said they could tolerate is the same risk they can actually live with. Our FiduciWho Short on how risk feels different when it shows up uninvited is a useful reminder that financial readiness and emotional readiness are not always identical.
Time also changes the consequences of both good and bad decisions. The Short Time Magnifies the Good and the Bad reinforces why habits, costs, diversification, and discipline matter over long periods.
The goal is not to pretend volatility is painless. It is to build a strategy that anticipates uncertainty rather than being surprised that uncertainty exists.
Understand What You Own Before You Buy It
I have a simple rule of thumb: if you cannot explain what you own to a fifth grader, you probably need to understand it better before putting meaningful money into it.
That does not mean every investment must be simple. It means your reason for owning it should be understandable.
If you are evaluating an individual company, you should have some idea of what it sells, who its customers are, how it makes money, what could threaten the business, and why you believe it may become more valuable over time.
Brian learned this lesson through experience. His early stock picks lost money, but the mistakes forced him to confront the difference between buying a ticker symbol and understanding a business.
That distinction matters because speculation can easily disguise itself as investing. A popular stock, compelling story, or exciting new technology does not eliminate the need to understand what you are buying.
The same principle applies to professional advice. Complexity should not be used to hide a weak explanation. Clarity should come before complexity.
Victor Haghani’s conversation on making smarter investment decisions instead of relying on intuition alone offers another useful perspective on bringing discipline to investment choices.
Financial Statements Matter for Investors and Business Owners
Brian compares investing without understanding financial statements to trying to become a serious musician without learning to read music. You may be able to play a few notes, but you are missing an important part of the language.
Financial statements help tell the story of a company.
An income statement provides insight into revenue, expenses, and profitability. A balance sheet helps explain what a company owns, what it owes, and the financial resources supporting the business. Those numbers do not tell you everything, but they provide a foundation for asking better questions.
This lesson is just as important for entrepreneurs.
Some business owners know every operational detail but cannot confidently explain their own income statement or balance sheet. That can make it harder to understand margins, cash needs, debt, profitability, and ultimately the value of the company they are building.
A business that depends entirely on the owner’s labor may produce a good income without necessarily becoming a valuable, transferable enterprise. Knowing the numbers can help an owner distinguish between having a high-paying job and building an asset.
Our FiduciWho Short on why business owners should learn to read financial statements reinforces the same point: better financial understanding creates a stronger foundation for better decisions.
You Do Not Have to Become an Individual Stock Picker
There is an important difference between learning how markets work and deciding that you need to become an expert stock picker.
Brian enjoys digging into businesses. Not everyone does, and that is okay.
Researching individual companies requires time, discipline, and a willingness to study financial statements, business models, competition, management, and valuation. Someone who has no interest in doing that work should not feel pressured to turn investing into a second career.
Diversified approaches can provide another way to participate in markets without attempting to identify individual winners. The appropriate investment strategy depends on a person’s objectives, time horizon, financial circumstances, tax situation, liquidity needs, and tolerance for risk, so individual decisions should be discussed with a qualified professional.
The broader lesson is to match the strategy to the investor rather than chasing whatever happens to be popular.
Our Short explaining why you cannot consistently count on outsmarting the market is relevant here. A durable financial strategy does not need to depend on predicting next week’s winning stock.
That also reflects the thinking behind FiduciWho Part 2: Grow Your Wealth: growth should be intentional, connected to your objectives, and built on a foundation that makes sense for your financial life.
Starting Small Can Make Financial Education Less Expensive
Brian’s early investing mistakes were painful, but the dollar amounts were relatively small. That gave him room to learn before the stakes became much larger.
There is wisdom in learning early.
People sometimes postpone financial education because they believe money becomes important only after they accumulate a large amount of it. I would argue the opposite. Understanding the basics before your financial life becomes complicated can make future decisions easier.
You can learn what diversification means. You can understand why risk and return are connected. You can learn how a company makes money. You can understand fees, taxes, account types, and basic financial statements before a six-figure portfolio or business sale forces you to learn under pressure.
Today, financial education is widely available through books, podcasts, videos, articles, and courses. Access to information is no longer the biggest barrier. The harder part is developing the discipline to separate useful education from noise, hype, and promises that sound too good to be true.
Learning should make your financial life clearer, not encourage you to constantly trade, chase trends, or turn every market headline into an emergency.
The Real Goal Is Not Beating the Market
People can spend enormous amounts of time deciding where to vacation, what television series to watch next, or which new purchase they want to make while giving relatively little attention to the financial plan that supports all of those choices.
Investing deserves attention, but investing is not the final objective.
The objective is the life behind the portfolio.
That is why my framework remains Protect, Grow, Enjoy, and Transfer.
Protect first. If a setback can dismantle your financial life, pursuing growth without addressing those risks may leave the entire plan vulnerable.
Grow second. Growth helps create the resources that may support future independence, retirement, family goals, and opportunities.
Enjoy third. Wealth should serve a life. The purpose is not simply accumulating a bigger number on a statement.
Transfer last. A thoughtful legacy plan can help clarify how assets, values, responsibilities, and opportunities may move to the people and causes that matter to you.
Stock market returns are one piece of that framework. They are not the framework itself.
That is also why Brian’s explanation is so useful. If you understand that markets represent real businesses rather than a mysterious machine, it becomes easier to put investing back in its proper place: as a tool for building the freedom, security, family life, purpose, and impact that matter to you.
Final Thoughts
So, why does the stock market go up? At the most basic level, it can rise over long periods because businesses grow, innovate, serve customers, and create value. That does not mean the path is smooth, every company succeeds, or future returns are guaranteed.
The bigger lesson from Brian Feroldi is that investing becomes easier to approach when you understand what is happening underneath the price movements.
Learn what you own. Know the numbers when you choose to analyze individual businesses. Respect volatility. Avoid building your future around the hot stock of the week. Most importantly, remember that investing is supposed to support a financial plan, not replace one.
Your dreams matter, and your future is our priority. A thoughtful plan can help you protect what you have built, grow it with purpose, enjoy the life it supports, and ultimately transfer wealth according to what matters to you.
If you are unsure how your investment strategy fits into that larger picture, consider discussing your goals, risk tolerance, time horizon, and financial circumstances with a qualified financial professional before making investment decisions.
Frequently Asked Questions
Why does the stock market go up over time?
The stock market can rise over long periods because the businesses represented in the market may grow, innovate, serve more customers, reinvest, and create additional economic value. Short-term declines still occur, and long-term growth is not guaranteed.
Why does the stock market recover after crashes?
Market recoveries can occur as uncertainty changes, investor expectations improve, and businesses continue adapting and producing value. The timing and strength of any recovery are uncertain, which is why past recoveries should not be treated as guarantees of future results.
Do I need to understand financial statements before buying stocks?
Anyone evaluating individual companies can benefit from understanding basic financial statements because they provide information about revenue, expenses, profitability, assets, liabilities, and financial condition.
Do investors need to pick individual stocks to build wealth?
No. Individual-stock investing is only one approach. Diversified investment strategies are also available, and the appropriate approach depends on personal goals, risk tolerance, time horizon, liquidity needs, and other financial circumstances.
How should investors deal with stock market volatility?
A financial strategy should account for the possibility of market declines before they occur. Diversification, an appropriate risk level, a long-term perspective, and a plan tied to personal goals can help provide context when markets become volatile.
What role should the stock market play in a financial plan?
Investing can help support long-term financial goals, but it is only one part of a broader plan that may also address protection, cash flow, retirement, taxes, estate considerations, family priorities, and legacy.